Claims software has become very good at moving information around. What should insurance carriers prepare for in 2027?
A customer reports a loss. The system creates a file, checks the policy, requests documents, assigns work and sends a payment. On a product demo, everything moves with the confidence of a perfectly choreographed airport baggage system.
Real claims are less cooperative.
The damage photograph may not match the loss description. A contractor may submit a second estimate. A storm may produce 10,000 new claims before the first 1,000 have been assigned. The customer may upload the same document through three channels because nobody told them the first upload worked.
That is why the familiar claims-system checklist—digital FNOL, automated workflows, analytics, integrations and payments—is no longer enough.
Those capabilities were important when I discussed modern claims management systems in 2024 but much has changed in 2027 plans. They remain the foundation. AI is increasingly being introduced into intake, triage, document processing, fraud detection and customer communication—but adoption remains uneven.
Regulators are paying closer attention to the decisions those systems support. Insurers are also learning that more automation does not automatically produce a simpler claims experience.
The real change is that a claims platform must now manage the claim’s uncertainty, not just move the claim’s paperwork.
That is the standard insurers should apply when selecting a claims management system for 2027.
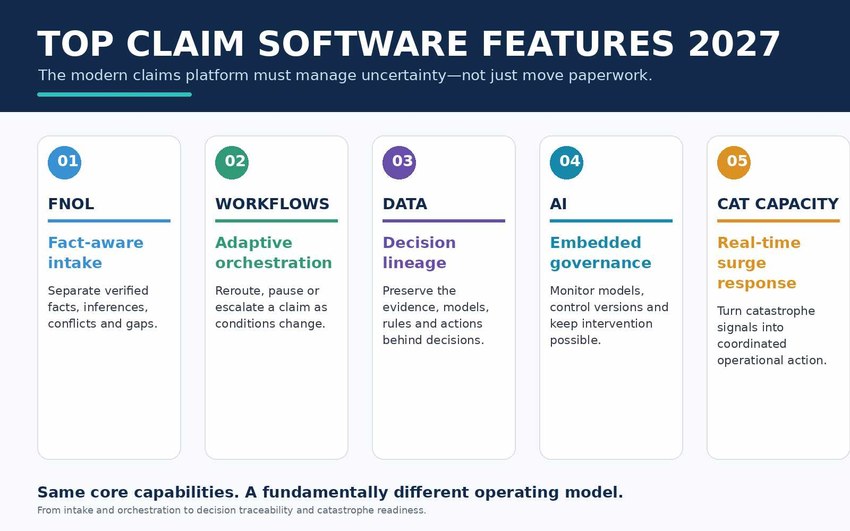
1. FNOL that knows the difference between a fact and a guess
A digital FNOL process is table stakes now. Customers can report losses through an app, website, call center or agent. They can upload photographs, videos, documents and sometimes telematics data before an adjuster ever sees the file.
The interesting question is what the system believes it knows after all that information arrives.
Imagine a homeowner reporting roof damage after a Tuesday storm. The weather feed confirms the storm. The customer’s photographs show damaged shingles. An image model identifies possible hail damage. The contractor’s invoice mentions long-term wear.
That is not one clean answer. It is a small committee of evidence, and the committee does not agree.
A more advanced claims system should preserve those differences instead of flattening them into a single confident-looking data field.
The customer’s statement, the weather record, the image model’s output and the contractor’s observation do not carry the same weight. One is reported information. One is external confirmation. One is an inference. One may be an expert assessment.
If the system treats all four as fact, that assumption can affect coverage review, fraud screening, severity, assignment and settlement.
So the stronger FNOL requirement is not just to capture all data but to show the insurer what is verified, what is inferred, what conflicts and what still needs to be established.
That may sound like a modest feature, but it could be what prevents a very expensive misunderstanding later.
2. Workflow Automation that Knows When to Stop
In 2024, workflow automation mainly meant moving claims through a defined sequence. The system assigned tasks, requested documents, sent notifications and applied business rules.
That works well when the claim stays on the expected path. Claims, as a group, have never shown much interest in doing that. A straightforward liability claim may turn into a dispute. A catastrophe may turn an ordinary assignment queue into a parking lot.
It is important that if you are planning for an advanced claim management system, it should be able to:
-
Reroute a claim when new evidence changes its complexity.
-
Pause a claim when information conflicts.
-
Escalate a claim when model confidence falls.
-
Assign work according to adjuster expertise and capacity.
-
Change priorities during a catastrophe.
-
Return a claim to automation after human review.
-
Record why the route changed.
Deloitte describes this broader problem as an “orchestration gap.” Insurers have accumulated AI capabilities for separate tasks, but greater value comes from connecting them through shared data, orchestration and governance. In claims, that can mean linking eligibility checks, document extraction, classification and routing instead of operating each capability in its own silo.
The platform should also distinguish between a missing document, a suspected fraud pattern, a coverage dispute and a catastrophe capacity problem. Sending all four to one generic “manual review” queue is not orchestration. It is a digital traffic jam with better branding.
Also Read: The Silent Risk in Core Insurance Systems (Antony Xavier, CEO, SimpleSolve Inc. )
3. Data Architecture that Preserves Why the Decision Happened
Connecting claims data was an important priority in 2024. It remains essential.
But AI has introduced a second problem. One claims decision may now involve policy data, external data, document extraction, image analysis, fraud scoring, business rules, vendor information and human judgment.
Months later, the insurer may need to explain why a claim was escalated, delayed, paid or denied.
A basic audit trail may show that someone changed a claim status. It may not show what information led to the change.
The more advanced requirement is decision lineage: preserving the evidence, rules, model outputs and human actions that shaped a material decision.
For a claim routed to investigation, the system should be able to show:
-
Which policy version applied.
-
What information was available.
-
Which documents, images and external data were used.
-
Which model and model version produced an output.
-
Which rule triggered the next action.
-
Whether an adjuster accepted or overrode the recommendation.
-
What happened afterwards.
This helps with more than regulatory reviews and litigation. It can show why work is slowing down. A delay may be caused by poor intake information, a document-extraction error, a third-party data dependency, an over-sensitive fraud rule or an approval bottleneck. Without decision context, all of those problems can look like a staffing issue.
However, this is only true for sophisticated AI-supported claims decisions, but for a large portion of the market, this is still an emerging maturity requirement, not today's universal baseline.
The NAIC’s AI guidance emphasizes documentation, transparency, governance and decision traceability. It also makes clear that insurers remain responsible for decisions affecting consumers when third-party models or data providers are involved.
4. AI Governance that Works Inside Claims
In 2024, insurers were exploring AI for file summaries, document processing, fraud detection, triage and damage assessment. The conversation focused largely on what these tools might achieve.
For insurers moving AI from experimentation into production, the question becomes how those systems behave over time. An AI output may influence whether a claim receives further investigation, what an adjuster sees first, how quickly a claim moves or whether it enters an automated settlement path.
The governance challenge is no longer only whether a model was approved. It is whether the insurer can detect when the model’s output starts abruptly changing claims outcomes. This follows the NAIC’s AI Systems Evaluation Tool
An insurer should also be able to suspend, change or replace a model without rebuilding the claims process around it. The model should be a controlled component—not a black box holding the workflow hostage.
5. Catastrophe Capacity That Adapts in Real Time
Insurers can already use third-party tools to overlay weather footprints with policies in force, aerial imagery and existing claims. The more important 2027 capability is whether the claims management system can bring those signals into the operational workflow.
It should identify affected policyholders, estimate incoming volume, open catastrophe workflows, route straightforward losses to digital handling, and assign complex claims according to adjuster skills, licensing, workload and vendor capacity.
The real advance is not another weather dashboard. It is a claims platform that turns external catastrophe data into coordinated action before the queue becomes a parking lot.
What Makes a Claims System Modern Now?
The five capabilities haven't fundamentally changed since 2024. What has changed is the relationship between them.
FNOL generates the information that feeds triage. Triage determines the workflow. The workflow draws on connected data and AI capabilities. Human intervention is introduced where the evidence or circumstances require judgment. Financial outcomes then provide another layer of information about the claim.
The value comes from that chain working as one system.
That is also why buying claims technology feature by feature is becoming less compelling. An insurer can have excellent document extraction, sophisticated fraud analytics and automated payments and still deliver a fragmented claims operation if those capabilities don't share context.
To learn more about our comprehensive range of insurance solutions, request a demo or call us at 609-452-2323
Topics: Claims Management